Financial Econometrics · Economics

Rodrigo Herrera

Associate Professor of Economics (tenured)
University of Talca, School of Business and Economics.

I am an economist specialising in financial econometrics. My research focuses on modelling the dynamics of extreme events and systemic tail risk in financial markets. I hold a PhD in Economics from Dresden University of Technology in Germany.
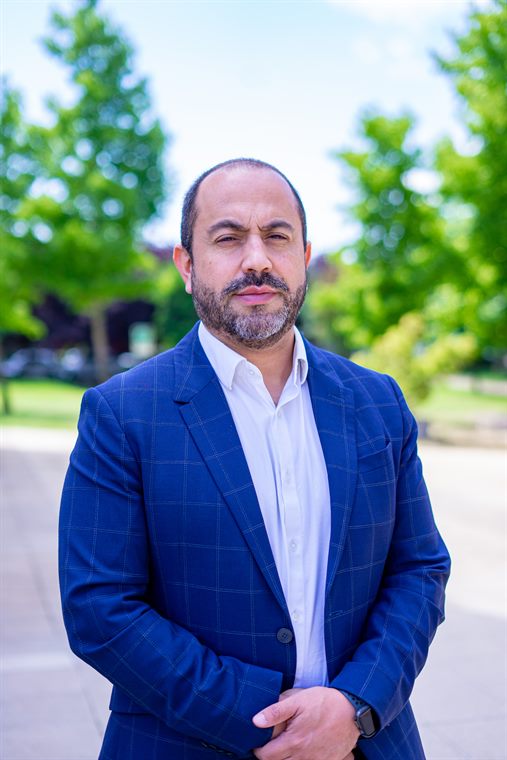
Rodrigo Herrera
RH
University of Talca, Chile

The Black Swan Outline

Guide the black swan across a landscape of extreme events: tornados, crashes, storms, volcanoes, earthquakes. Each pipe is a section: stand on it and press ↓ to enter. Move with ←→ / A–D, jump with Space. Collect the EVT parameters (ξ, β, μ, σ) to build the extreme-value theorems in the clouds, and stomp The Denier along the way.

THE BLACK SWAN OUTLINE← → move · SPACE jump · ↓ enter

The Black Swan Outline

A tiny platformer through tornados, crashes, storms & systemic risk. Every pipe is a section of my site.

31
Peer-reviewed publications
7
Funded projects (PI)
4
Erdös number
Citation metrics

Research

I am an economist working to understand how markets behave and what that means for the broader economy, with particular attention to rare but economically consequential events. Financial crises are, statistically, tail events: infrequent but consequential, so my research models their timing and intensity rather than the calm middle of the distribution, and traces how extreme risk in one market spills over into others and into the real economy.

Methodologically, I work at the intersection of extreme value theory, point processes, and score-driven (observation-driven) time-series models, building tools to forecast Value at Risk, Expected Shortfall, and systemic tail risk. Empirically, I apply them to banking, commodities, electricity, and currency markets, often with high-frequency and option-implied information.

Extreme value theory

Peaks-over-threshold and self-exciting models for the dynamics of rare market events.

Quantitative risk management

Forecasting VaR, Expected Shortfall and expectiles; evaluating and backtesting tail risk.

Systemic & spillover risk

How extreme risk propagates across banks, commodities and energy markets.

News

Sep 2026
“Can uncertainty affect extreme events in the oil market? A MIDAS touch to dynamic POT models” (with K. Bień-Barkowska and A. Kliber) published in the Journal of Empirical Finance, 89, 101768.
Sep 2026
“Modeling tail risk spillovers in commodity markets: The dominant role of energy” (with C. Candia and K. Bień-Barkowska) published in the Journal of Commodity Markets, 43, 100577.
Mar 2026
Appointed Director of the PhD Program in Economics at the University of Talca.
2026
Appointed to the evaluation committee (study group) of FONDECYT–ANID, Chile’s National Agency for Research and Development, from 2026.
2025
Program committee member for IFC 2026; organizing sessions at the conference.
2024
Elected member of Chile’s Copper Reference Price Advisory Committee.

Publications

Selected below · full list expandable
Selected
2026
J. Empirical FinanceCan uncertainty affect extreme events in the oil market? A MIDAS touch to dynamic POT models. Bień-Barkowska, K., Kliber, A. and Herrera, R. 89, 101768.
2025
Int. J. ForecastingWhen to be discrete: The importance of time formulation in the modeling of extreme events in finance. Bień-Barkowska, K. and Herrera, R.
2025
J. Empirical FinanceTail risk dynamics of banks with score-driven extreme value models. Fuentes, F., Herrera, R. and Clements, A. 81, 101593.
2023
Int. J. ForecastingForecasting extreme financial risk: A score-driven approach. Fuentes, F., Herrera, R. and Clements, A. 39(2), 720–735.
2020
J. Applied EconometricsMultivariate dynamic intensity peaks-over-threshold models. Hautsch, N. and Herrera, R. 35(2), 248–272.
Show full publication list (31)
WoS & Scopus articles
2026
Can uncertainty affect extreme events in the oil market? A MIDAS touch to dynamic POT models. Bień-Barkowska, K., Kliber, A. and Herrera, R. Journal of Empirical Finance, 89, 101768.
2026
Modeling tail risk spillovers in commodity markets: The dominant role of energy. Candia, C., Herrera, R. and Bień-Barkowska, K. Journal of Commodity Markets, 43, 100577.
2024
An empirical review of dynamic extreme value models for forecasting Value at Risk, Expected Shortfall and Expectile. Herrera, R. and Candia, C. Journal of Empirical Finance, 77, 101488.
2024
Risk modelling with option-implied correlations and score-driven dynamics. Piña, M. and Herrera, R. North American Journal of Economics and Finance, 72, 102136.
2023
Diversification benefits of commodities in portfolio allocation: A dynamic factor copula approach. Gaete, M. and Herrera, R. Journal of Commodity Markets, 32, 100363.
2021
A non-parametric statistic for testing conditional heteroscedasticity for unobserved component models. Rodriguez, A., Pino, G. and Herrera, R. Journal of Applied Statistics, 48(3), 471–497.
2020
Network analysis: a novel approach to identify PM2.5 hotspots and their spatio-temporal impact on air quality in Santiago de Chile. Clements, A., Herrera, R. and Hurn, A. Air Quality, Atmosphere and Health, 13, 1075–1082.
2020
Dynamics of connectedness in clean energy stock markets. Fuentes, F. and Herrera, R. Energies, 13, 3705.
2020
A marked point process model for intraday financial returns: Modelling extreme risk. Herrera, R. and Clements, A. Empirical Economics, 58, 1575–1601.
2019
Geographical spillovers on the relation between risk-taking and market power in the US banking sector. Pino, G., Herrera, R. and Rodriguez, A. North American Journal of Economics and Finance, 47, 351–364.
2018
Modeling extreme risks in commodities and commodity currencies. Herrera, R., Clements, A. and Fuentes, F. Pacific-Basin Finance Journal, 51, 108–120.
2018
A dynamic multiple equation approach for PM2.5 forecasting in Santiago, Chile. Moisan, S., Herrera, R. and Clements, A. International Journal of Forecasting, 34, 566–581.
2018
Mutual excitation between OECD stock and oil markets: A conditional intensity extreme value approach. Herrera, R. and González, S. North American Journal of Economics and Finance, 46, 70–88.
2018
Point process models for extreme returns: Harnessing implied volatility. Herrera, R. and Clements, A. Journal of Banking and Finance, 88, 161–175.
2018
Are crude oil and natural gas extreme prices interdependent? Herrera, R. and Fuentes, F. Journal of Physics: Conference Series, 1053, 012112.
2017
Modeling and forecasting extreme commodity prices: A Markov-Switching based extreme value model. Herrera, R., Rodriguez, A. and Pino, G. Energy Economics, 63, 129–143.
2015
Modeling interregional links in electricity price spikes. Herrera, R., Clements, A. and Hurn, A. Energy Economics, 51, 383–393.
2014
Statistics of extreme events in risk management: The impact of the subprime and global financial crisis on the German stock market. Herrera, R. and Schipp, B. The North American Journal of Economics and Finance, 29, 218–238.
2014
Modeling and forecasting of extreme events in electricity spot markets. Herrera, R. and González, N. International Journal of Forecasting, 30(3), 477–490.
2014
New evidence of contagion in the Asian crisis. Herrera, R. and Karmann, A. Review of Development Economics, 18(2), 354–371.
2013
Energy risk management through self-exciting marked point process. Herrera, R. Energy Economics, 38, 64–76.
2013
Value at Risk forecasts by extreme value models in a conditional duration framework. Herrera, R. and Schipp, B. Journal of Empirical Finance, 23, 33–47.
2011
Extreme dependence with asymmetric thresholds: Evidence for the European Monetary Union. Herrera, R. and Eichler, S. Journal of Banking and Finance, 35(11), 2916–2930.
Book chapters
2009
Self-exciting extreme value models on stock market crashes. Herrera, R. and Schipp, B. In: Statistical Inference, Econometric Analysis and Matrix Algebra, Physica-Verlag Heidelberg, 209–231.
2007
Reliability models for the uncapacitated facility location problem with user preferences. Herrera, R., Nickel, S. and Kalcsics, J. In: Operations Research Proceedings 2007, 135–140.
Other publications (in Spanish)
2007
Análisis comparativo de eficiencia técnica entre la banca chilena y alemana. Aguirre, M., Herrera, R. and Bravo, G. Revista de Matemática: Teoría y Aplicaciones, 14(2), 203–218.
2004
Una frontera de producción para la banca chilena. Aguirre, M., Herrera, R. and Bravo, G. Panorama Socioeconómico, 29.
Working papers & work in progress (5)
Climate Shades in the Tail: Systemic Risk across Green and Brown Stocks in the S&P 500. Muñoz, E. and Herrera, R. Submitted, Econometrics and Statistics.
Score-driven VARtime: A multivariate framework for tail risk forecasting. Herrera, R., Candia, C. and Clements, A.
Using threshold-based volatility for estimating linear HAR model coefficients. Herrera, R. and Clements, A.
Realized conditional intensity of extreme events from a high-frequency perspective. Herrera, R. and Clements, A.
Dynamic binary models for extreme risk in financial markets. Herrera, R. and Bień-Barkowska, K.

Software

Open-source · on GitHub
RVARtime, a multivariate dynamic model for forecasting extreme financial risk. MIT license.
MATLABWhen to be Discrete: replication code, reproducibility materials for the International Journal of Forecasting (2025) paper on time formulation in modelling extreme events.

Teaching & Advising

Postgraduate: Financial Econometrics, Advanced Econometrics, Time Series, Quantitative Finance, Quantitative Risk Management, Quantitative Methods & Data Science, Research Methodology.

Undergraduate: Econometrics, Stochastic Modelling, Stochastic Frontiers, Productivity Analysis, Optimization, Operations & Logistics, Supply Chain Management.

Doctoral students supervised
2026
E. Muñoz: Green and brown stocks, common volatility and climate risk (Assistant Professor, Universidad Católica del Maule, Chile).
2024
C. Candia: Three tales of extreme financial risk (now Assistant Professor, Universidad de Concepción).
2021
F. Fuentes: Multivariate time-varying extreme value models in finance (now Assistant Professor, University of Talca).

Master’s advisees include M. Piña (now PhD student, University of Virginia), M. Gaete, T. Pérez and S. Moisan. Full details in the CV.

Selected invited talks
2026
Society for Financial Econometrics (SoFiE) Annual Conference, Macao.
2024
Society for Financial Econometrics (SoFiE) Annual Conference, Rio de Janeiro.
2022
LACEA LAMES Annual Meeting, Lima.
2021
LACEA LAMES Annual Meeting, Bogotá.
2020
12th Econometric Society World Congress, Milan.

… and 60+ conferences, seminars and workshops worldwide. Full list in the CV.

Funding

Principal Investigator unless noted
2026–2029
FONDECYT Regular
(equivalent to the NSF in the United States)
Modelling and forecasting extreme financial events in the era of generative artificial intelligence.
Principal Investigator
2021–2024
FONDECYT Regular Nº 1210915
Systemic tail risk: new directions for understanding high-dimensional extreme financial risk.
Principal Investigator
2018–2020
FONDECYT Regular Nº 1180672
Modeling high-dimensional and high-frequency extreme events in financial markets: trading activity, liquidity measures, and news flow.
Principal Investigator
2015–2017
FONDECYT Regular Nº 1150349
Extreme financial risk: a multivariate conditional framework of extreme events.
Principal Investigator
2015–2019
CYTED
Iberoamerican Network of Agro-Bigdata and Decision Support Systems.
Co-researcher
2011–2013
FONDECYT Initiation Nº 11110247
Advanced extremal models for risk modeling under Basel II.
Principal Investigator
2011
DAAD_CRUCH
Extreme value theory with applications in risk management and crisis contagion.
Principal Investigator

Appointments & Service

2018–24
Dean, School of Economics and Business, University of Talca.
2026–
Member, evaluation committee (study group), FONDECYT–ANID (National Agency for Research and Development, Chile).
2024–
Elected member, Copper Reference Price Advisory Committee, Government of Chile: technical guidance on official copper price projections.
2023–
Board member, International Finance Conference (program committee & session organizer, IFC 2026).
2018–
Member, EfD Research Nucleus on Environmental and Natural Resource Economics.
2016–19
Board member, Chilean Economic Society (SECHI).
Reviewer for Energy Economics, Journal of Empirical Finance, International Journal of Forecasting, Journal of Futures Markets and others; referee for FONDECYT and Becas Chile.
Visits
Visiting researcher at: University of Oxford (Saïd Business School, 2025); Warsaw School of Economics (SGH, 2025); University of Chile (2025); University of Edinburgh (2024); Queensland University of Technology (2013, 2014, 2016–2019); Erasmus University Rotterdam (2016); Humboldt-Universität zu Berlin (2010, 2012); Dresden University of Technology (2012); Karlsruhe Institute of Technology (2009); and Universität des Saarlandes (2007).

Six Degrees of Collaboration

Erdös, Einstein & Gauss numbers

An Erdös number counts the co-authorship steps that separate me from Paul Erdös; the same idea gives an Einstein and a Gauss number. Mine are 4, 6 and 8. Each dot is a real co-author along the shortest published path. More about the Erdös number →

“If I have seen further it is by standing on the shoulders of giants.”Isaac Newton, 1675 · nanos gigantum humeris insidentes

Contact

Phone
+56 71 2200308
Office
Escuela de Ingeniería Comercial, Facultad de Economía y Negocios, Universidad de Talca, Avenida Lircay s/n, Talca, Chile.
BibTeX copied to clipboard